Form 5472: How Many Forms for Related Parties?
File a separate Form 5472 for each related party with reportable transactions, all attached to the reporting entity’s return.

Form5472 Prep
Reviewed filing guidance for foreign-owned LLCs
Plain English
No dense tax-code language
Actionable
Clear next steps and deadlines
Current
Last updated August 28, 2026
Last updated: September 2026
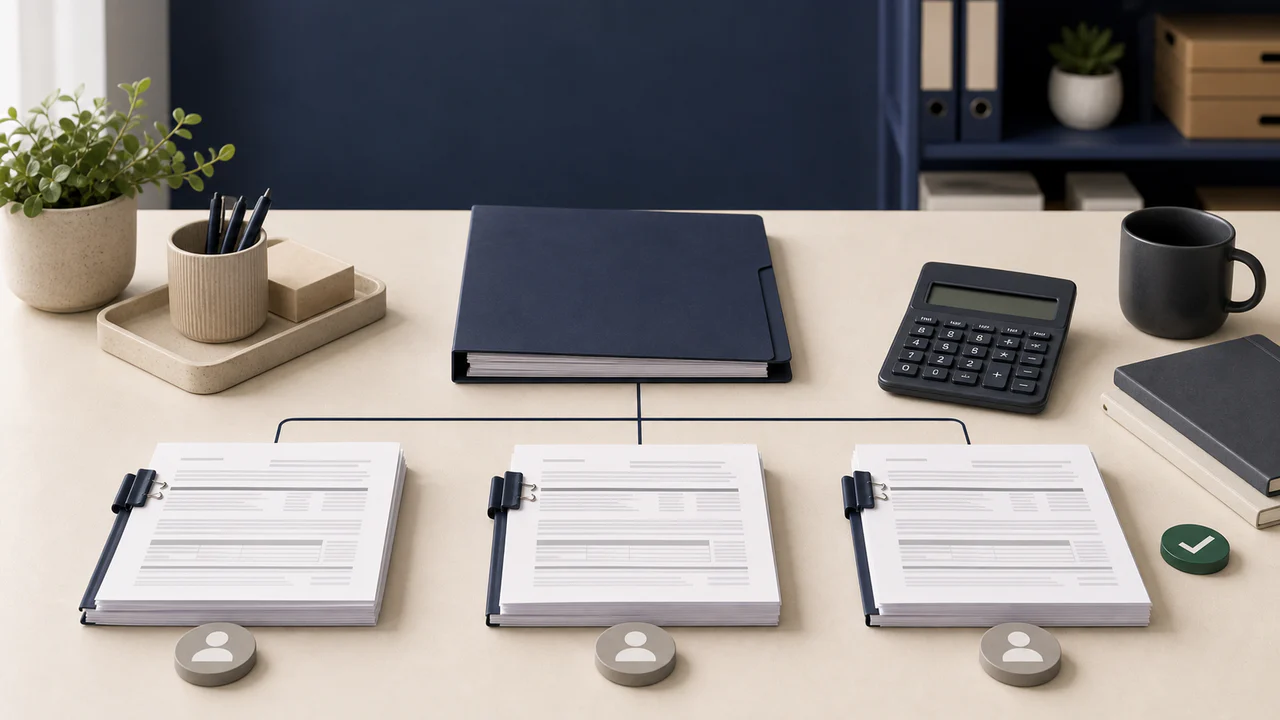
A reporting LLC files a separate Form 5472 for each related party with which it had a reportable transaction during the tax year. Multiple transactions with the same person normally stay on that person’s form. Transactions with the foreign owner, a related foreign company, and another related person can therefore require three Forms 5472 attached to one filing package.
If the ownership chart has more than one related counterparty, start the filing and identify each party separately.
What does the one-form-per-related-party rule mean?
The IRS Instructions for Form 5472 direct filers to file a separate Form 5472 for each foreign or U.S. related party with reportable transactions. Line 1g reports the total number of Forms 5472 filed for the tax year.
The organizing unit is the related party, not the transaction. Ten reportable transfers with one owner generally belong on one Form 5472. One transfer each with three different related parties can require three forms.
Who is a related party?
A related party can include the 25% foreign shareholder and people or entities related through ownership, control, or specified family and tax-law relationships. An unrelated vendor does not become related merely because it is foreign.
Use the Form5472 Prep relationship map:
| Counterparty | Example | Separate Form 5472? |
|---|---|---|
| Foreign owner | Owner contributes and withdraws cash | Usually yes |
| Owner’s controlled foreign company | Company invoices U.S. LLC for development | Potentially yes |
| Unrelated foreign contractor | Contractor provides design services | Generally no |
| Family-controlled company | Relative’s company sells inventory to LLC | Requires relationship analysis |
| U.S. related person | Related domestic counterparty | Can still fall within the rule |
The definition is technical. Common ownership and indirect ownership should be reviewed before deciding a party is unrelated.
How are several forms reconciled?
Build one schedule per related party:
- Assign the party’s legal name and consistent identifier.
- List every monetary and nonmonetary transaction with that party.
- Classify and total the transactions in U.S. dollars.
- Prepare one Form 5472 for that party.
- Reconcile the party totals to the aggregate values reported in Part I.
The current Form 5472 includes lines for the total number of forms and total foreign-related-party transaction values. The aggregate should equal the sum of the individual related-party schedules.
What if the foreign owner is also the service provider?
One person can have several roles without requiring several forms. If the owner contributed capital, lent money, and received service fees, those transactions can be reported on the one Form 5472 for that owner, with each category shown accurately.
A separate legal entity controlled by the owner is a different counterparty. The owner’s personal form should not absorb the company’s invoices merely because the same individual controls both.
How does Form5472 Prep handle multiple parties?
The guided intake identifies each related party and builds separate supporting totals. Complex ownership, transfer pricing, or entity-classification issues may need specialist advice, but the filing service can prepare the information-return package for supported cases.
Start your filing and disclose every potentially related counterparty before submission.
Frequently asked questions
Do I file one Form 5472 per foreign owner?
File one for each related party with reportable transactions. A foreign owner with no reportable transaction may present a different analysis from an owner who funded or received money from the LLC.
Do multiple transfers require multiple forms?
Not when all transfers involve the same related party. Group that party’s transactions on the party-specific form and supporting statement.
Are foreign contractors related parties?
Not solely because they are foreign. Ownership, control, family, and specified tax relationships determine related-party status.
Does each Form 5472 carry a separate penalty risk?
The IRS instructions apply the continuing penalty with respect to each related party for which a failure occurs. Complete party-by-party reporting is important.
When several related parties are involved, the Form 5472 penalty calculator can help separate per-form exposure from the underlying transaction totals.
The bottom line
Count related parties, not bank transfers. Prepare one Form 5472 per related party, reconcile every party schedule to the aggregate filing, and keep unrelated vendors outside the related-party bucket. Get the complete package prepared and faxed.
Educational content only; not tax or legal advice.